Slab Leak Insurance Help in Indio, CA

Understanding how property insurance treats foundation plumbing failures, tear-out costs, and the technical documentation required for claim adjusters.

Schedule Diagnostic Report: (888) 205-7875
Policy Fundamentals

How Homeowners Insurance Typically Evaluates Slab Leaks

Discovering water weeping through foundation concrete or baseboards immediately prompts the question: does homeowners insurance cover slab leaks Indio residents file? While individual policies differ, insurance carriers generally divide a slab leak claim into three distinct categories:

  1. The Tear-Out / Access Cost: The labor and expense required to access the leak, including electronic leak detection, breaking through concrete, or opening walls to reach the pipe. In standard California HO-3 policies, tear-out to access a plumbing failure is frequently covered.
  2. The Resulting Water Damage: Damage caused to flooring, drywall, baseboards, cabinets, and carpet due to accidental discharge of water is typically covered, subject to deductible and policy exclusions.
  3. The Pipe Repair Itself: The actual copper fitting, PEX pipe, or solder coupling used to mend the pipe is often considered normal homeowner maintenance and excluded from reimbursement.

Notice: The information provided on this page is for general educational purposes and does not constitute legal or insurance advice. Every homeowner must review their specific policy declarations and consult their insurance agent.
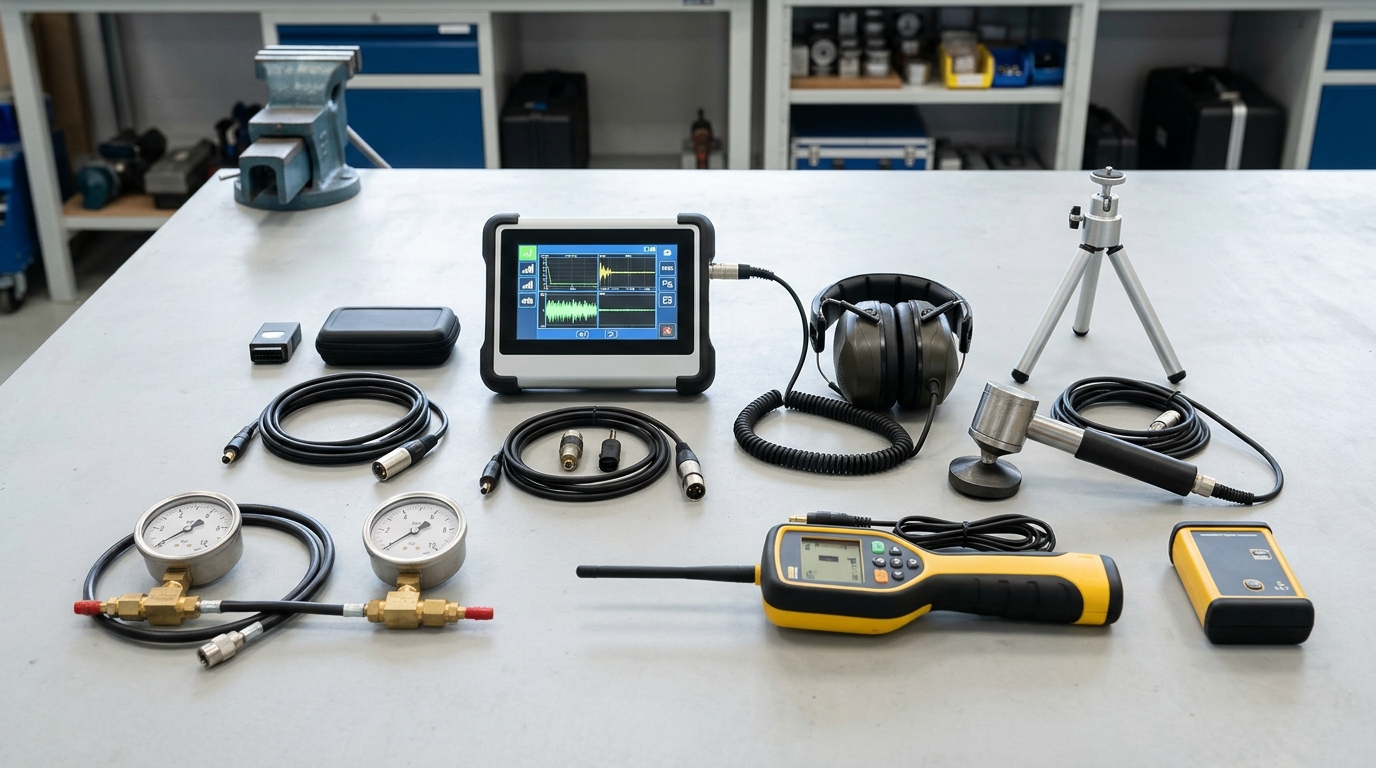
Plumbing technician preparing electronic leak detection documentation report for insurance adjuster
Detailed electronic detection logs and photographic reports provide adjusters with objective evidence of subterranean line failures.
Claim Documentation

The Three Pillars of Slab Leak Documentation Indio Adjusters Require

Insurance claims are approved based on objective physical evidence. Here is the documentation our diagnostic team provides:

Document 1

Electronic Detection Log

A certified technician report specifying acoustic spike frequencies, thermal imaging photographs with temperature differentials, and hydrostatic pressure decay logs proving a sudden accidental pipe failure.

Document 2

Timestamped Photo Record

High-definition photographic documentation of the damaged pipe, moisture meter readings along wall plates, and initial water damage to floors and baseboards taken before remediation begins.

Document 3

Itemized Scope of Work

A line-item invoice that cleanly separates electronic diagnostic access fees from the plumbing pipe repair, allowing your insurance adjuster to process covered access costs without confusion.

Need Documentation for Your Insurance Adjuster?

We provide formal written diagnostic reports detailing leak location, thermal imaging maps, and cause of failure. Call our office to schedule inspection.

Call (888) 205-7875
Action Steps

Steps to Take Right Away When Filing a Slab Leak Insurance Claim Indio

Handling the initial hours of a water leak properly protects both your physical property and your coverage rights:

  1. Mitigate Immediate Damage: California policyholders have a contractual duty to mitigate ongoing damage. Turn off the main water valve and wipe up standing water immediately to stop mold growth.
  2. Do Not Discard Damaged Materials: Keep carpet scraps, baseboards, or excised pipe sections in the garage for your insurance adjuster to inspect in person.
  3. Obtain Professional Leak Detection First: Contact a specialist to confirm the leak before filing a claim. If damage is minor and well beneath your deductible, you may decide not to file a claim on your record.
  4. Compare Reroute vs. Demolition: Many insurance carriers prefer an overhead slab leak reroute because bypassing the line costs less than jackhammering and restoring custom travertine or hardwood flooring.

Reviewing Repair Options

Whether your property requires an overhead PEX bypass, spot repair, or complete whole-house repiping, our reports provide clear technical rationale for your insurance provider. Read more about slab leak repair in Indio on our homepage.

Frequently Asked Questions

Insurance Claim Questions Answered

Will my insurance pay for an overhead PEX reroute instead of breaking the slab?

In many circumstances, yes. Adjusters recognize that the combined cost of jackhammering concrete, restoring foundation footings, and matching expensive imported flooring often costs thousands more than a clean overhead reroute.

Does insurance cover long-term slow leaks?

Policies frequently contain exclusions for "continuous or repeated seepage" over weeks or months. Having electronic detection that documents a sudden pressure drop helps demonstrate that the leak was a sudden, accidental failure.

Can you talk directly with my insurance adjuster?

While we cannot negotiate coverage on your behalf, we readily provide adjusters with our full technical report, thermal imaging data, photographic records, and itemized diagnostic invoices.